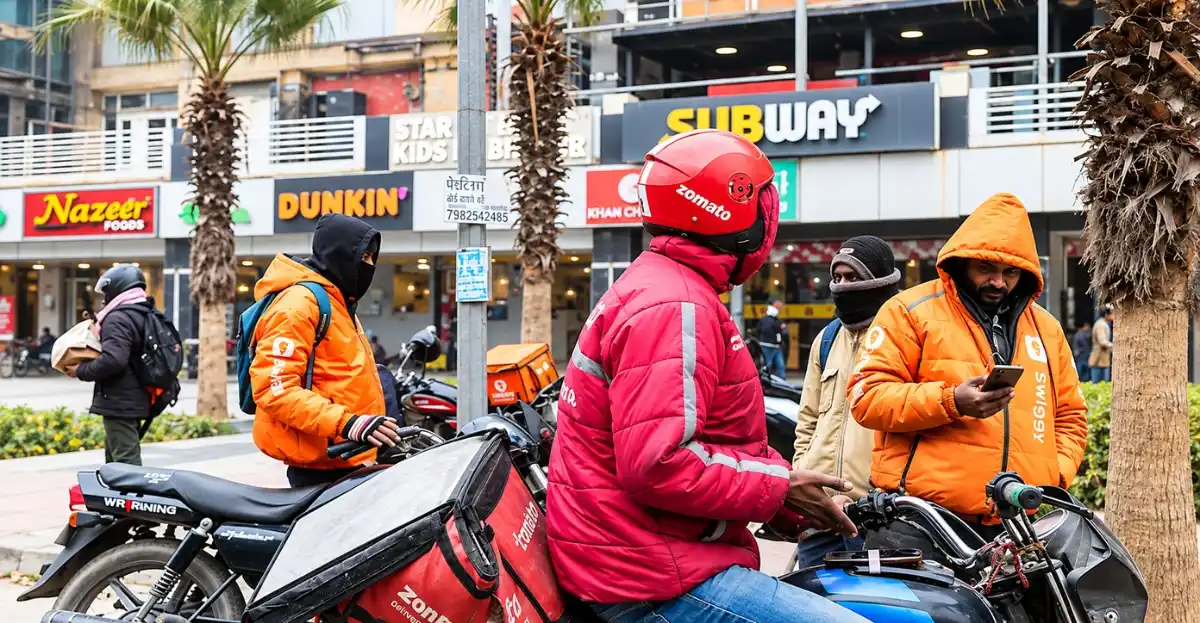
Gig worker social security in India stopped being a policy debate on 21 November 2025, when the Code on Social Security, 2020 finally came into force. Since 8 May 2026, when the central rules were notified, it has also been a compliance task with deadlines attached.
If you run HR, finance or operations at a platform company, the Code lands on your desk directly. If you hire freelancers or contract talent, it lands more quietly, through classification and contract risk. This guide covers both, and says plainly where the rules are still unsettled.
What does the Code say about gig worker social security in India?
The Code on Social Security, 2020 recognises gig workers, platform workers and aggregators in Indian law for the first time. It doesn’t make them employees. It creates welfare schemes funded by aggregator contributions of 1% to 2% of annual turnover, capped at 5% of what the aggregator pays its workers.
Section 2(35) defines a gig worker as someone who earns from work outside a traditional employer-employee relationship. A platform worker is a narrower group: people who work through an online platform. The scheme-based design is the key point. Gig workers get access to government-notified schemes, not a PF or ESI account in their name.
Where things stand in October 2026
| Date | What happened |
| 21 November 2025 | The Code on Social Security came into force |
| December 2025 | Draft central rules were published |
| 8 May 2026 | Final Social Security (Central) Rules, 2026 notified |
| 21 June 2026 | Deadline for aggregators to upload existing workers (45 days from commencement) |
| 30 June / 31 October | Annual dates for provisional self-assessment and final return, once a contribution is payable |
That last row matters this month. Contribution returns are due 31 October, but the contribution itself only starts once the Central Government notifies the rate and commencement date for each aggregator category. The most recent analyses I could find, from June and July 2026, still describe that notification as pending. Check the Ministry of Labour and Employment’s site before you assume either way.
Are you an aggregator? Most employers aren’t
An aggregator is a digital intermediary that connects a buyer of a service with the person delivering it. Ride-hailing, food and grocery delivery, e-marketplaces and logistics platforms are the obvious cases, and the Seventh Schedule of the Code lists the categories that can be asked to contribute.
The definition is wider than it first looks. Reporting on the final rules notes that it reaches associate companies, holding companies, subsidiaries and LLPs, not only the app itself. If your group structure routes gig work through a related entity, that entity may be the one on the hook.
A company that hires a freelance designer or a contract data analyst directly is generally not an aggregator. Its exposure is different, and I’d argue it’s the bigger risk for most readers of this blog: calling someone a gig worker when the day-to-day reality looks like employment. Fixed hours, a manager who assigns tasks, no freedom to work for anyone else. Labour inspectors and courts tend to look at that reality, not at the contract title.
How the aggregator contribution works
Section 114(4) sets the band. Under the Social Security (Central) Rules, 2026, an aggregator calculates its contribution on annual turnover (excluding central taxes, cess and surcharges), subject to the 5% payout cap. Late, short or missed payments attract interest of 1% a month.
The cap is easier to see with numbers. These are illustrative figures, not a real company.
- A platform has ₹500 crore in turnover and pays ₹300 crore to workers. At 2%, the contribution is ₹10 crore. The cap is 5% of ₹300 crore, which is ₹15 crore. The cap doesn’t bite.
- Same turnover, but only ₹100 crore goes to workers. At 2%, the contribution would be ₹10 crore, but the cap is ₹5 crore. The cap applies.
So a marketplace that keeps most of the value it handles pays less than the headline percentage suggests. A labour-heavy platform feels the full band.
Who qualifies: the 90-day and 120-day test
A worker becomes eligible for benefits only after 90 days with one aggregator, or 120 days across several, in the previous financial year. The rules count a day if the worker earned any income that day, however small.
This is a data problem before it’s a legal one. Can your systems say, for each worker, on which dates they earned something? Many can’t, especially where payouts run through a third-party agency. The rules also require new workers to be registered in real time and exits to be reported, so a monthly spreadsheet won’t hold up.
Related Posts
What employers should do now
- Settle the aggregator question in writing: Get your legal team or counsel to confirm whether your company, or a group entity, falls in a Seventh Schedule category. Record the reasoning.
- Clean the worker data: You’ll need identity details, engagement dates and earnings per day, in a form that can be sent to the portal. Fixing this after a notice arrives is far more expensive.
- Register on the Shram Suvidha portal: If you missed the 21 June upload window, do it anyway and document the delay. The rules require real-time onboarding and exit reporting from then on.
- Model the contribution at both ends of the band: Run 1% and 2% against your turnover, then apply the 5% payout cap. Put the 30 June and 31 October dates in the finance calendar now.
- Audit classification: List everyone you engage outside payroll and check the working reality against the contract. Fix the mismatches while it’s your choice to fix them.
What’s still unclear
Several things aren’t settled, and anyone who tells you otherwise is guessing.
The benefits themselves haven’t been spelled out. The Code mentions life and disability cover, accident insurance, health and maternity benefits and old-age protection, but reporting on the 2026 rules points out that no scheme had been notified under Section 114 when they came out. The contribution rate and start date for each category were also still pending in the sources I reviewed.
States are moving separately. Karnataka and Rajasthan have their own platform worker laws with their own welfare boards, so a platform operating nationally may answer to more than one regime.
The part HR teams tend to skip
Compliance is the visible work. The less visible work is what your treatment of flexible workers says to the people on your payroll.
Our view at Amazing Workplaces is that employees watch how a company handles its most exposed workers and draw conclusions about how it would handle them in a bad year. A delivery partner without cover and a full-time employee in the same company aren’t living in separate stories. We’ve surveyed more than 60,000 employees since 2018, and fairness is a thread running through nearly every conversation about trust.
That’s also why we’d treat this Code as a retention and brand question, not only a legal one. If you’re thinking along those lines, our piece on why retention is now a business continuity issue is a useful companion. And if you want an outside read on how your people practices look from the inside, the Amazing Workplaces survey and certification is built for that.
FAQs
Do gig workers get PF and ESI under the new Code?
Not in the traditional sense. The Code creates government-notified schemes for gig and platform workers, funded by aggregator contributions. It doesn’t enrol them in EPF or ESIC as employees.
Is every company that hires freelancers an aggregator?
No. An aggregator is a digital intermediary in a listed category. A business engaging freelancers directly generally isn’t one, though it should still check that its freelancers aren’t employees in practice.
What happens if an aggregator pays late?
The 2026 rules set interest at 1% per month, or part of a month, on late, short or unpaid contributions. Separate penalties under the Code may also apply.
This article is general information, not legal advice. The rules are still being operationalised, so confirm current notifications with qualified counsel before acting.